SUBSCRIBE TO OUR FREE NEWSLETTER
Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
5
#000000
#FFFFFF
To donate by check, phone, or other method, see our More Ways to Give page.

Daily news & progressive opinion—funded by the people, not the corporations—delivered straight to your inbox.
Sen. Elizabeth Warren is reportedly preparing to grill bank CEOs and push for a cap on credit card interest rates, among other policies.
Poised to take over as head of the Senate Banking Committee in the new Congress starting in January, progressive US Sen. Elizabeth Warren of Massachusetts is reportedly preparing to use her powerful role to investigate Wall Street banks and other big corporations accused of profiteering at the expense of working-class Americans.
An unnamed aide to Warren on the banking panel told Politico that "Big Tech CEOs, administration officials, Trump family crypto businesses, Wall Street executives, and giant corporations should preserve their documents and prepare to answer tough questions."
In addition to Warren's planned "oversight blitz," the senator also intends to "pursue affordability-centered policies," including "capping credit card interest rates, cracking down on what she calls 'corporate profiteering,' and pursuing a new bipartisan housing bill with soon-to-be ranking member Tim Scott (R-SC)."
"She’s also planning to continue teaming up with Republican China hawks to restrict exports of advanced AI chips, the aide said," according to Politico. "Nvidia CEO Jensen Huang, a key figure in that push, is also expected to be a top oversight target."
In a social media post on Sunday, Warren argued that Democrats won historic midterm victories "by recognizing Americans’ economic pain, denouncing Washington corruption that has made a rigged economy worse by favoring giant corporations over working people, and by pledging to upend this system."
"Americans need Democrats to deliver now," the senator wrote.
As head of the Senate Banking Committee, Warren would have significant power to demand testimony from corporate executives and advance subpoenas to force companies to hand over documents.
Reuters reported late last week that Warren "will likely probe the Office of the Comptroller of the Currency's August decision to approve a bank charter for President Donald Trump-backed World Liberty Financial."
"She is also likely to investigate the administration's mass firings of financial agency workers and its attempts to shut down the Consumer Financial Protection Bureau, an agency she helped create," Reuters added.
"Anthropic is saying that AI models could pose catastrophic or existential risks to humanity. At the same time, Anthropic is planning the largest IPO in history."
As the artificial intelligence company Anthropic moves toward a historic initial public offering, the top Democrat on the US Senate Banking, Housing, and Urban Affairs Committee sounded the alarm about both public safety and financial concerns in a Tuesday letter to CEO Dario Amodei.
"I write with concern following your company's disclosure that Anthropic's advanced AI models could 'pose catastrophic or existential risks to humanity' at the same time that it seeks to register as a public company and sell shares in November," said Sen. Elizabeth Warren (D-Mass.).
"Anthropic disclosed extensive public safety and financial risks to the Securities and Exchange Commission (SEC) as part of its registration process for an initial public offering (IPO)," she noted. "An IPO would provide Anthropic with broader access to the largest capital markets in the world, allowing it to raise more funding from a larger pool of investors to fuel its rapid growth."
"It will also mean that millions of Americans with retirement accounts invested in index funds will quickly become Anthropic shareholders," stressed the former Harvard University bankruptcy professor. "Public pensions are already heavily exposed to Anthropic and have expressed their concerns about Anthropic's societal risks ahead of its IPO."
According to the SEC paperwork, Anthropic plans to list on the Nasdaq under ticker symbol "ANT." Reports have suggested the company—known for its Claude models—could be valued at between $1.5 trillion and $2 trillion. As NPR noted: "That would put it in league with Elon Musk's rocketry and AI company SpaceX, which was valued at around $1.8 trillion when it listed in June."
Warren pointed out to Amodei that "this massive influx of public capital is likely to catapult the development and deployment of your technology during a time of intense public debate and concern about the risks of your frontier intelligence models."
The senator argued that "the risks presented by this technology demand greater scrutiny before they become intertwined with the public capital markets, which could further escalate both public safety and systemic financial risks."
The "growing public safety concerns" section of Warren's letter cites details from the Form S-1 that Anthropic submitted to the SEC, as well as the CEO's public statements "calling for the need to slow down the development of frontier AI models."
"You warned that 'we still only understand a tiny fraction of what goes on inside these models' and highlighted the 'risk of losing control of AI systems, misuse of AI for cyberattacks and bioterrorism, and serious economic disruption,'" she reminded Amodei. "You further warned that a 'race to the bottom, spurred by commercial incentives, can make these risks more acute.'"
"It is also difficult to trust existing safety tests and evaluations of model test environments in the wake of recent incidents in which models built by frontier AI companies, including Anthropic, have broken through security controls and hacked external systems autonomously," the senator emphasized.
Such incidents have intensified AI experts' warnings and spurred calls for government action, leading to a range of legislative proposals, including in the US Congress—the future control of which will be decided in next week's midterm elections.
Warren highlighted that "in addition to the potentially catastrophic safety risks posed by Anthropic's technology, the company's launch into the public markets could inject extreme volatility and risk into the financial system, which threatens to undermine Americans' economic security."
"Anthropic is projected to be the largest IPO in history," she wrote. "Given its unprecedented size, swings in Anthropic's share price have the potential to roil the broader markets on day one, particularly for companies in the technology sector, and even more acutely for megacap companies with direct financial entanglement with Anthropic."
"Beyond the threats to the financial system that Anthropic's IPO may pose, the company's registration statement disclosures include astronomical projections supported by aggressive assumptions that require further review and due diligence," she added, digging into the company's disclosures.
Warren also sent Amodei a detailed list of questions she wants answered by November 3—before the company goes public.
"Trump's Iran War has forced Americans to pay much more at the pump while Big Oil rakes in profits and the president's own stock wealth in the oil and gas industry continues to balloon."
After US President Donald Trump spent the weekend reminding midterm campaign rally attendees that he doesn't "give a damn" about soaring gasoline prices from his illegal Iran War, congressional Democrats on Monday released a report showing that his oil and gas stock holdings could now top $80 million.
During a Saturday rally in Georgia, Trump highlighted that due to his war of choice, the US fossil fuel industry is "making hundreds of billions of dollars," and predicted his comments will be turned into "fake headlines," but he added: "I don't give a damn, I'm going to say it: We're making a freaking fortune."
Just how much extra is the public paying at the pump because of the eight-month conflict? As of Monday, the national average was $4.29 a gallon for gasoline and $6.35 for diesel, according to the American Automobile Association.
An online tracker from the Climate Solutions Lab at Brown University estimates US residents have paid at least $144.6 billion more for fuel—$79.8 billion for gasoline and $64.79 billion for diesel. That's over $609 per household, just for gasoline.
Data from the congressional Joint Economic Committee suggest the impact could be even worse. As JEC Democrats' Monday report notes, the panel found that US households "have now spent an additional $101 billion on gasoline since the start of the Iran War, or an average of $856 in gas costs per family."
A state-by-state breakdown in the report—released just days ahead of the midterm elections that will determine control of Congress for the remainder of Trump's second term—reveals that price increases for gasoline have hit some areas particularly hard. Wyoming, a Republican stronghold, has had the highest hike per household, at $1,454.
Rounding out the top 10 are Utah ($1,240), Alabama ($1,232), Montana ($1,180), Mississippi ($1,141), South Dakota ($1,122), Idaho at ($1,108), North Dakota ($1,087), New Hampshire ($1,029), and Iowa ($1,010). Trump won all of those states but New Hampshire in 2024—when he campaigned on a promise to serve the interests of the climate-wrecking fossil fuel industry if its executives dumped $1 billion into his run, while also claiming he would lower costs for working people.
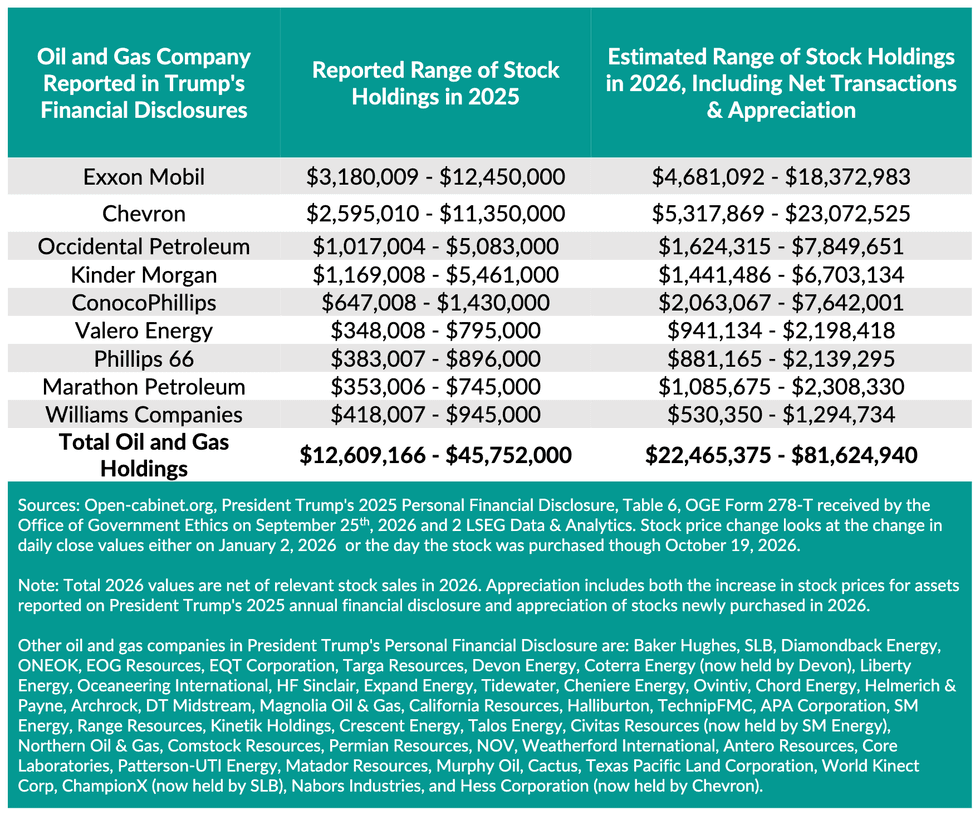
Meanwhile, the report stresses, Trump's oil and gas holdings could have nearly doubled this year, growing by as much as $35.8 million, for a total of up to $81.6 million—and 94% of his 2026 industry stock purchases occurred after he went to war with Iran, which has restricted ship traffic through the Strait of Hormuz.
The document details Trump's holdings—which are reported in ranges—in Chevron, ConocoPhillips, ExxonMobil, Marathon Petroleum, Occidental Petroleum, Phillips 66, Valero Energy, and Williams Companies. It also warns that "the true value may in fact be higher given that Trump has yet to report stock transactions for September or October, and because he has a history of filing his transactions much later than the law requires."
Sen. Maggie Hassan (D-NH), the JEC's ranking member, declared that "Trump's Iran War has forced Americans to pay much more at the pump while Big Oil rakes in profits and the president's own stock wealth in the oil and gas industry continues to balloon."
Trump has faced scrutiny and criticism for cashing in on the conflict he created, which the White House has tried to dismiss by pointing out that the president's "stock and bond portfolio is independently managed by third-party financial institutions."
Such comments have not appeased critics, including Hassan, who said that "as Trump—the country's highest-ranking public employee—continues to own and trade stocks in companies that stand to benefit from his decisions, his actions raise major concerns about conflicts of interest. Unfortunately, this is nothing new from this administration and only reinforces that the president puts his own financial interests above the American people."
This article has been updated to credit the Climate Solutions Lab at Brown University for its fuel cost tracker.
"Americans should expect fair application of the rule of law to ensure even the most powerful and well-connected can be held accountable."
A report released by government watchdog Public Citizen Wednesday reveals how, under the Trump administration, a donation to or partnership with President Donald Trump "could make your legal matters disappear."
When Trump took office in January 2025, he inherited from the Biden administration hundreds of enforcement actions that were supposed to be carried out against law-breaking corporations.
But as Public Citizen research director Rick Claypool wrote in the report, titled "Trump’s Cascade of Canceled Corporate Enforcement Against Over 200 Corporations," the president and his top officials have rolled back 212 enforcement actions against 205 corporations since taking office—closing dozens of federal investigations, dismissing 67 lawsuits that federal agencies were actively litigating, and terminating numerous other consequences for wrongdoing.
Ninety of the companies that have avoided enforcement actions—44%—were ones with ties to Trump, including 53 that contributed to the president's inaugural committee, super political action committees (PACs) that supported him, or the demolition of the East Wing of the White House to make way for Trump's ballroom.
“Trump’s retreat from law enforcement against corporate crime is a signal to Big Business that if you’re big enough, rich enough, and connected enough with Trump’s inner circle, there are no consequences for breaking the law,” said Claypool. “The reckless experiments of AI corporations, the proliferation of scammy financial fraudsters, and the outbreaks of tainted food show that the message has clearly been received.”
Elon Musk, the CEO of Tesla and SpaceX, is one of the largest beneficiaries of Trump's retreat, following his pouring of $400 million into the president's campaign and those of other Republicans in 2024. He also gave $1 million to the president's inaugural fund and $5 million to the MAGA, Inc. super PAC.
Tesla has benefited from four canceled enforcement actions, with the National Highway Traffic Safety Administration canceling three investigations and the Department of Labor canceling an inspection into contract compliance. Lawsuits that had been filed against SpaceX by the Department of Justice and the National Labor Relations Board were also closed, as was an Environmental Protection Agency investigation into data center pollution.
Musk himself also avoided a lawsuit over alleged misconduct when he purchased the social media platform X, when the Securities and Exchange Commission suit was dismissed.
Pfizer, which employed former Attorney General Pam Bondi before she joined the Trump administration—only to be fired earlier this year—also had three enforcement actions canceled. The pharmaceutical giant contributed $1 million to Trump's inaugural fund.
Wall Street giant Wells Fargo has also benefited from the cancellation of five enforcement actions, and Amazon, Bank of America, Meta, and Polymarket are among the corporations that have had at least two canceled.
The report explains how other corporations across the Big Tech, finance, and cryptocurrency sectors have seen investigations and lawsuits vanish after contributing to Trump's reelection efforts, including:
"Americans should expect fair application of the rule of law to ensure even the most powerful and well-connected can be held accountable," reads the report. "But with 44% (90 out of 205) of corporations with publicly known ties to the administration receiving the benefit of canceled enforcement, the pattern of favoritism toward corporate insiders is clear."
Claypool emphasized that by working unilaterally and wielding his executive power instead of collaborating with Congress, Trump has granted the "corporate wish" of canceled enforcement actions "with relative ease."
"Unlike passing friendly legislation, which requires coordination and cooperation with congressional majorities, or formal deregulation, which can require formal processes including outside input intended to ensure careful and deliberate decision making, agency leaders derelict in their duties claim canceling enforcement is a matter merely of prosecutorial discretion," reads the report.
The analysis details several executive actions and policies Trump has unilaterally adopted "to reduce enforcement against corporate crime and lawbreaking," including:
The administration has also been able to cancel enforcement in a "top-down" fashion through its "dismissal of DOJ independence" and the Supreme Court's ruling in Trump v. Slaughter, which permitted the White House to seize authority from regulators.
"The result," wrote Claypool, "is that power over federal agencies is more concentrated than ever with the president’s inner circle—and that courting favor with President Trump is a distinctly powerful lever for taking advantage of the enforcement retreat."
"The Trump SEC is seeking to bail out the struggling private equity and private credit industry with hardworking Americans' retirement savings."
The US Securities and Exchange Commission on Wednesday proposed policies that SEC Chair Paul Atkins framed as an effort to promote private market investments by retail investors—or everyday Americans—while also "protecting those investors from bad actors and fraud," but critics accused the Republican-dominated federal agency of serving Wall Street at the expense of the public.
"Chair Atkins talks about the 'responsible retailization' of the private markets, but the rules the SEC proposed today are irresponsible," declared Benjamin Schiffrin, director of securities policy for the nonprofit Better Markets. "The SEC is supposed to protect retail investors from risky private market assets. Instead, it is encouraging investors saving for college and retirement to direct their savings to private market investments that do not offer greater returns but that do offer less disclosure and more limited legal recourse when harmed."
"Although hedge funds may charge fees based on performance to their investors, the SEC has long prohibited investment advisers from charging retail investors performance-based fees," Schiffrin explained. "This protects them from arrangements that might encourage advisers to take undue risks with retail client funds to increase their compensation. Yet the SEC's proposed rules would make such arrangements permissible. This change would eliminate a limitation on the ability of private funds that charge performance-based fees to sell to retail investors and would incentivize advisers to push retail clients into risky private funds that have performance-based fees."
The new rules would also make it easier to sell interval funds, which "hold complex and illiquid assets and charge high fees," Schiffrin noted. "Given that many interval funds have faced heightened redemption requests from existing investors seeking to exit these funds in recent months, now hardly seems like the time to further expose retail investors to these funds."
“Perhaps most troublingly, the SEC expands the categories of individuals who qualify as so-called 'accredited investors' to whom private market assets may be sold," he continued. Specifically, the agency said it is considering letting individuals with some certificates or licenses—such as certified public accountants, research analysts, and financial analysts and planners—qualify.
"Accredited investors are supposed to be institutions and individuals with enough assets to bear the risk of loss inherent in private market assets," Schiffrin stressed. "Now, the SEC would allow individuals to qualify as accredited investors without regard to their ability to lose money in the private markets."
The expert also highlighted the timing of these proposals, pointing to the agency's Monday statement that "reminded the private funds industry of its obligations regarding valuing assets and providing disclosure to investors," which Schiffrin said was "obviously intended to provide cover for the SEC's desired expansion of the private markets."
"Having previously downplayed the turmoil in the private credit markets, continued redemption requests by private credit investors forced the SEC to acknowledge that private market assets are particularly risky and to reassure investors it was not asleep at the switch," he said. "Yet the statement begs the question of why the SEC would seek to expose retail investors to the private markets at the same time it acknowledges the risks that private market assets pose even to institutional investors."
"The answer is that the SEC has lost its way," he concluded. "Its agenda is now the financial industry's agenda, and private funds need access to retail investors and their savings as institutional investors increasingly pull back from private markets. So the proposed rules the SEC issued today have nothing to do with 'democratizing access' to the private markets and everything to do with allowing the financial industry to prey on unsuspecting retail investors."
The SEC chair said Wednesday that the agency's latest moves "complement efforts undertaken pursuant to" President Donald Trump's August 2025 executive order on Democratizing Access to Alternative Assets for 401(k) Investors—which Schiffrin warned last year "exemplifies the administration's determination to prioritize the interests of Wall Street over the interests of Main Street and retail investors."
"Let's be clear: Neither 401(k) plan sponsors or 401(k) plan participants—regular, hardworking Americans—are asking to replace stocks and bonds in their 401(k)s with risky private assets," Schiffrin said at the time. "Instead, the private funds industry needs a way to get its hands on the $12 trillion in Americans' retirement accounts to boost its profits and make up for the fact that institutional investors are fleeing the private markets due to mediocre returns, higher fees, and more risk."
Despite such criticism of Trump's order, the US Department of Labor unveiled its related proposal in March. Jim Baker, executive director of the nonprofit Private Equity Stakeholder Project, pointed to the pending DOL policy in a Wednesday statement responding to the SEC action.
"With the proposed rules, combined with the DOL's 401(k) rule, the Trump SEC is seeking to bail out the struggling private equity and private credit industry with hardworking Americans' retirement savings," he said. "Private equity funds have lagged public markets while charging much higher fees, and institutional investors are pulling back from the asset class. These rules risk shifting more financial risk onto workers who rely on their retirement savings for long-term security."
"Private equity firms are already under pressure from a backlog of unsold assets and declining distributions to investors," Baker emphasized. “At the same time, policymakers are giving private equity access to retirement savers' 401(k) plans, raising serious questions about whether these investment risks are being shifted onto everyday retirement savers."
"Retirement accounts exist to provide security, not to bail out private market investments by shifting liquidity risk onto workers when markets turn," he added. "At a minimum, the SEC should hold private equity to the same disclosure and transparency standards expected of publicly traded stocks, mutual funds, and [exchange-traded funds], including clear reporting on what funds are investing in, the fees and expenses retirement savers are paying, the amount of debt funds are using, and how these investments are actually performing compared with stocks."
Key members of Congress also responded to the SEC's Wednesday proposals. While Republicans on the US Senate Banking, Housing, and Urban Affairs Committee welcomed the push to expand the accredited investor definition, which aligns with Chair Tim Scott's (R-SC) Empowering Main Street in America Act, Ranking Member Elizabeth Warren (D-Mass.) was critical.
"Today, the SEC proposed a new rule that would override decades-old protections for Americans' retirements to allow Wall Street to start charging high, private equity-level fees on lower-cost retail funds," Warren said. "Americans already struggling to save in Trump's economy shouldn’t be used as piggy banks to boost the profits of Trump’s Wall Street buddies."
"This brazen scheme is illegal many times over and is an affront to the basic principle that the government exists to serve the people, not to enrich cronies and insiders," said their lawyer.
A pair of watchdog groups on Thursday sued President Donald Trump and other US officials over their "pay-to-play" scheme that gives subscribers who fork over a monthly fee of up to $100,000 early access to key decision-makers' posts on Truth Social.
The president's Trump Media & Technology Group announced the social media platform's program in July, drawing swift criticism from ethics experts and Democratic lawmakers—including House Judiciary Committee Ranking Member Jamie Raskin (D-Md.), who opened a probe. Despite corruption concerns, Truth Application Programming Interface (API) launched early last month.
Because Truth API covers the accounts of Trump, as well as White House Deputy Chief of Staff Dan Scavino, Transportation Secretary Sean Duffy, Health and Human Services Secretary Robert F. Kennedy Jr., and Federal Bureau of Investigation Director Kash Patel, they are all named in the new suit—as is the president's executive assistant, Natalie Harp.
"It is no accident that the Truth API covers so many official government accounts," says the complaint, filed by American Oversight and Campaign for Accountability, in the US District Court for the District of Columbia. "Information the Trump administration disseminates on Truth Social through its official accounts can have significant consequences for the global economy."
"Truth API subscribers—who now receive this potentially market-moving information before the rest of the public—can profit on their early knowledge of what the Trump administration says, does, and believes," the filing stresses.
In other words, "the president is selling Wall Street faster access to official government announcements and lining his own pockets in the process," said American Oversight executive director Chioma Chukwu. "Like so much of his agenda, this scheme is built to benefit the wealthy and well-connected while the rest of us are pushed to the back of the line."
Gerstein Harrow attorney Samuel Davis, who is representing the groups, declared that "this brazen scheme is illegal many times over and is an affront to the basic principle that the government exists to serve the people, not to enrich cronies and insiders."
Specifically, "this two-tier system of access" not only "serves no legitimate public purpose" but also "is irrational, inequitable, and illegal under the First and Fifth Amendments to the US Constitution and the Paperwork Reduction Act," the complaint argues. After outlining the alleged violations of federal law, the filing asks the court to declare the scheme unconstitutional and unlawful.
"If President Trump has one talent, it is finding new and creative ways to monetize his presidency," Campaign for Accountability executive director Michelle Kuppersmith said of the man who has pocketed at least $2.2 billion—over half of it from his family's cryptocurrency endeavors—during his first year back in the White House, according to recent disclosures.
"In another era, Congress would be outraged and take immediate action, but since that's out of the question, a lawsuit offers the only possible remedy," Kuppersmith continued. "We look forward to discovery so the American public can learn exactly which companies are willing to pay up."
The suit—filed less than two months ahead of the November midterm elections in which Democrats aim to take control of both chambers of Congress from Trump's Republican Party—is not the first filed over Trump API. The Freedom of the Press Foundation (FPF) and the media outlet The Intercept sued last month in the Southern District of New York.
That pair—represented by Citizens for Responsibility and Ethics in Washington, Yale Law School's Media Freedom and Information Access Clinic, the Public Integrity Project, and Altshuler Berzon—filed a motion seeking a preliminary injunction earlier this month. The Intercept's CEO, Annie Chabel, said that "Trump doesn't get to charge people for his own public statements."
"The First Amendment doesn't have a paywall, and we're not going to let him build one," Chabel added. "Journalists and the public shouldn't have to pay the president for news he's constitutionally obligated to share with everyone."
"Doctors should be able to do what's best for their patients, not what's best for some wealthy investor."
Thanks to legislation passed in Oregon last year, physicians in the state have stopped corporate takeovers of medical practices—and six Democratic members of Congress on Wednesday introduced a bill to replicate the state law nationwide, arguing, as Sen. Elizabeth Warren said, that "patients want to know that decisions about their health are being made by their doctors, not by Wall Street investors."
The Massachusetts Democrat was joined by Sens. Ron Wyden (D-Ore.) and Jeff Merkley (D-Ore.), along with Reps. Val Hoyle (D-Ore.), Alexandria Ocasio-Cortez (D-NY), and Suhas Subramanyam (D-Va.) in introducing the Stop Corporate Takeovers of Physicians Act.
The bill would ban the corporate practice of medicine by making it illegal for private equity funds, insurance companies, and other for-profit corporations to own or control medical practices—as is increasingly the case in the profit-driven US healthcare system.
Over 80% of doctors in the US are employed by corporate entities including private equity firms—up from 62% just seven years ago, according to the lawmakers.
Corporations have also exploited legal loopholes that allow them to take over medical practices, despite laws in over 30 states banning the corporate practice of medicine.
“Americans want medical decisions to stay between patients and their doctor, not dictated by corporate actors and private equity firms focused on maximizing profits,” said Wyden. “I’m proud of Oregon’s pioneering state law that has been used by doctors to protect their independence, and it’s time to take that model to the federal level. Corporate medicine is making healthcare more expensive for everyone, and safeguards must be put in place to ensure healthcare decisions stay in the hands of physicians.”
The legislation would:
"But these actors often challenge the autonomy of acquired physicians once in control," they said. "For example, corporate entities often assume control over clinical operations, management and staffing decisions, and billing and coding practices—all of which can exert pressure on physicians to change care delivery."
Such entities "often cut corners, leading to patients paying more for significantly worse care," said Ocasio-Cortez. “I’m proud to co-lead the Stop Corporate Takeovers of Physicians Act to get Wall Street out of Americans’ doctors’ offices."
Warren added that "doctors should be able to do what's best for their patients, not what's best for some wealthy investor."
BREAKING: Today, I'm introducing a bill to BAN corporate takeovers of your doctor's office.
Doctors should be able to care for their patients without greedy private equity investors getting in the way.
Let's get this done. pic.twitter.com/e3gdamIotQ
— Elizabeth Warren (@SenWarren) September 16, 2026
The legislation is supported by several medical associations as well as economic justice advocates.
"A prohibition is only as strong as its enforcement, and this bill backs its corporate practice of medicine (CPOM) prohibition with three enforcement paths: the Federal Trade Commission, state attorneys general suing on behalf of residents, and physicians themselves through a private right of action with treble damages. That layered enforcement, paired with mandatory divestment, is what gives this bill teeth that earlier CPOM laws have often lacked,” said Dr. Marco Fernandez, president of the Association for Independent Medicine.
Alex Lawson, executive director of Social Security Works, said that the "groundbreaking legislation is absolutely needed to give health providers and patients a fighting chance against corporate greed."
"Congress must stop private equity from ripping the copper wires out of American healthcare and put patients first," said Lawson. "Social Security Works is proud to endorse this legislation."
Charles Idelson, the former communications director of National Nurses United, which advocates for Medicare for All, said the bill "would help close some, though not all, of the worst profiteering in healthcare."
"Exploiting sickness to enrich wealthy executives," said Idelson, "is obscene."
The president is making "significant profits on the global instability he's inciting," said one government ethics expert. "It's profoundly unethical."
In a mandated filing with the Office of Government Ethics released Thursday, President Donald Trump was found to have made more than 1,000 stock transactions in June, including thousands of dollars invested in energy companies that were reaping record profits from the war Trump started with Iran.
Trump submitted financial disclosure forms to the OGE covering the second quarter of 2026, during which the Iran War continued, was paused for a ceasefire, and restarted again.
CBS News pointed to a "notable large transaction" on April 7, the day Trump declared a ceasefire with Iran after having threatened to destroy the country's "entire civilization." His investment accounts sold between $500,000 and $1 million of ExxonMobil stock that same day.
The filings were submitted days after Democrats on the Joint Economic Committee (JEC) estimated that Trump's oil and gas stocks have soared in value since before he began attacking Iran in February—an act that raised oil prices due to Iran's retaliatory closing of the Strait of Hormuz. The holdings were estimated at $13 million to $46 million at the start of 2026 and $17 million to $61 million this month.
"President Trump saw his wealth go up by as much as $15.5 million just through stocks he owned in oil and gas companies at the end of 2025," said the JEC Democrats. "These companies’ profits and stock values are rising because Trump’s reckless war in Iran has caused gas and oil prices to skyrocket."
The JEC's estimates were based on his holdings in 2025 and did not account for the trades he continued to make as the war dragged on.
"Trump's war in Iran has inflicted higher energy and gas prices on the American people," said Citizens for Responsibility and Ethics in Washington (CREW). "Meanwhile, Trump's brokers have been trading oil and gas stocks for him, helping him profit on the global instability he's inciting. It's profoundly unethical."
The White House said the president does not make trades himself, but CREW president Donald Sherman told CBS News that Trump should not be making "significant profits on the global instability he's inciting."
"President Trump's war of choice in Iran has cost the American people in the form of higher energy and gas prices and higher shipping costs," Sherman said. "Meanwhile, Trump's brokers have been trading oil and gas stocks for him... It doesn't matter whether he's trading the stocks himself—the president has a duty to avoid conflicts of interest between his finances and what's best for the American people."
Unlike other US presidents, Trump has refused to place his assets in a blind trust, instead continuing to hold stocks that are visible to him in all 11 sectors involved in the stock market.
In June, the president's stock portfolio made a series of energy trades, including two sales and one purchase of ExxonMobil stock that were valued between $1,001 and $15,000. He also bought and sold Chevron stocks three times and made three sales of ConocoPhillips holdings.
Sen. Kirsten Gillibrand (D-NY) said that the new filings show "Trump's only focus is enriching himself at the expense of the American people."
An open letter to Trump's Treasury Secretary, whose economic analysis is, frankly... shite.
Dear Scott (if I may).
I’ve argued that the K-shaped economy — a term used to describe growing inequality between high- and low-income households — can be seen in sales of McDonald’s burgers, whose lower- and middle-income customers fell by double digits in the first quarter of 2025 as they struggled with affordability.
Last Monday, you criticized me, arguing that McDonald’s problems are instead due to competition from rivals like Burger King.
(By the way, Scott,Bill Clinton didn’t fire me and Berkeley won’t, either. But your boss has a well-recorded tendency to fire his Cabinet secretaries, so I’d be careful if I were you.)
In a recent interview on CNBC’s “Squawk Box,” you even declared that the U.S. economy is no longer in a K shape: “I got sick of hearing about this K-shaped economy. I can say here definitively, the K-shaped economy is over.”
As a former Cabinet secretary, I hope you won’t mind if I’m candid with a current one. Scott, your analysis is full of shite. It’s still a K-shaped economy.
Lower-income workers continue to struggle with stagnant wages and inflation, while high-income workers are riding high on the wealth effects of the stock market. Real wages may be growing slightly more for low income than high income, but the booming stock market is mostly benefiting the high income.
Widening inequalities are partly due to policies you and your boss in the Oval Office have been pursuing — especially your tariffs and war in Iran, both of which have been pushing prices upward and imposing a far greater burden on lower-income than high-income Americans.
July’s jobs report showed wage growth falling sharply, with average hourly earnings increasing at the slowest pace in five years — 3.2% year-over-year. Inflation, meanwhile, is not slowing. As a result, consumers’ purchasing power is falling. Prices are now rising 3.5% year-over-year, as wage growth has slowed to just 3.2% — meaning that the real earnings of Americans have been dropping since April.
And I’m not just talking about McDonald’s, Scott. When major retailers reported quarterly results in May, many noted the growing divide between high- and low-income consumers. Wealthier households continue to drive spending, while lower- and middle-income households struggle to keep up. “We certainly see with our higher-income consumers, they’re benefiting probably from the wealth effect of a buoyant stock market,” said Walmart’s CFO John David Rainey. “But with low-income consumers, they don’t necessarily get that benefit, and then it’s a little bit more of paycheck to paycheck.”
Grocery chains like Kroger are considering rolling back prices to gain market share in this K-shaped consumer environment. Target is also trying to adjust to it. We’re “expanding both low, low price points, starting at $1, all the way up to some of the new premium brands,” says Cara Sylvester, who became Target’s chief merchandising officer in mid-February.
On recent quarterly earnings calls, CEOs in grocery, outdoor apparel, and kids’ apparel noted the same K-shape pattern. Kevin Depew, deputy chief economist and industry eminence program leader at RSM, attributes what’s happening to an economy in which lower- and middle-income households face real spending pressure while upper-income consumers remain cushioned by equity gains. Home improvement retailer Home Depot notes the impact of higher fuel costs in particular. “There’s no question that the average consumer is feeling pressure from rising fuel costs,” Home Depot CFO Richard McPhail said.
Other major firms report that premium travel and high-end goods (luxury airline seats and high-tier tech products) have seen double-digit growth, while discount retailers and dollar stores report high demand for basic necessities from budget-constrained consumers.
Researchers at the Federal Reserve Bank of Kansas City confirm the same trend. After analyzing changes in consumer spending between 2021 and 2025, they found that households with high incomes (fourth and fifth quintiles) increased their spending substantially faster than did consumers with low incomes (first to third quintiles). Because inflation-adjusted wage growth for the bottom quartiles has lagged behind top earners, everyday expenses like groceries, rent, and insurance are consuming larger shares of lower-income budgets.
The Federal Reserve’s May Beige Book also reflects this K-shaped divide, noting that higher-income households have remained relatively resilient, while lower-income consumers are showing greater financial strain and increased reliance on credit.
According to Moody’s Analytics, the richest 10% of American earners — composed of households making about $250,000 a year or more — are driving a record 49.7% of total U.S. consumer spending, significantly boosting the economy through the wealth effect of higher stock and home prices. They own over 90% of the value of all shares of stock, so big gains in the stock market have encouraged them to splurge on everything from vacations to designer handbags. “The finances of the well-to-do have never been better, their spending never stronger and the economy never more dependent on that group,” says Mark Zandi, who oversaw the analysis, based on data from the Federal Reserve. Zandi says the K-shaped economy remains “firmly intact.”
All told, rich Americans have increased their spending far beyond inflation, but nobody else has. The bottom 80% of earners spent 25% more than they did four years earlier, barely outpacing price increases of 21% over that period. And they’re going into debt to do so (researchers find auto repossessions and credit card delinquencies rising among lower-to-middle-income borrowers). But the top 10% spent 58% more.
Research by U.S.Bank also shows the K-shaped economy’s divide across household balance sheets, labor market access, generational wealth-building, and sector performance. “Higher-income households are more likely to own homes, equities, and retirement assets,” says Matt Schoeppner, senior economist for U.S. Bank, “allowing them to participate more directly when financial markets and home values rise.”
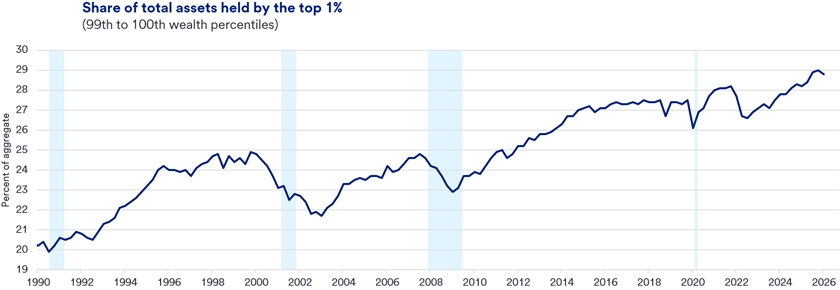
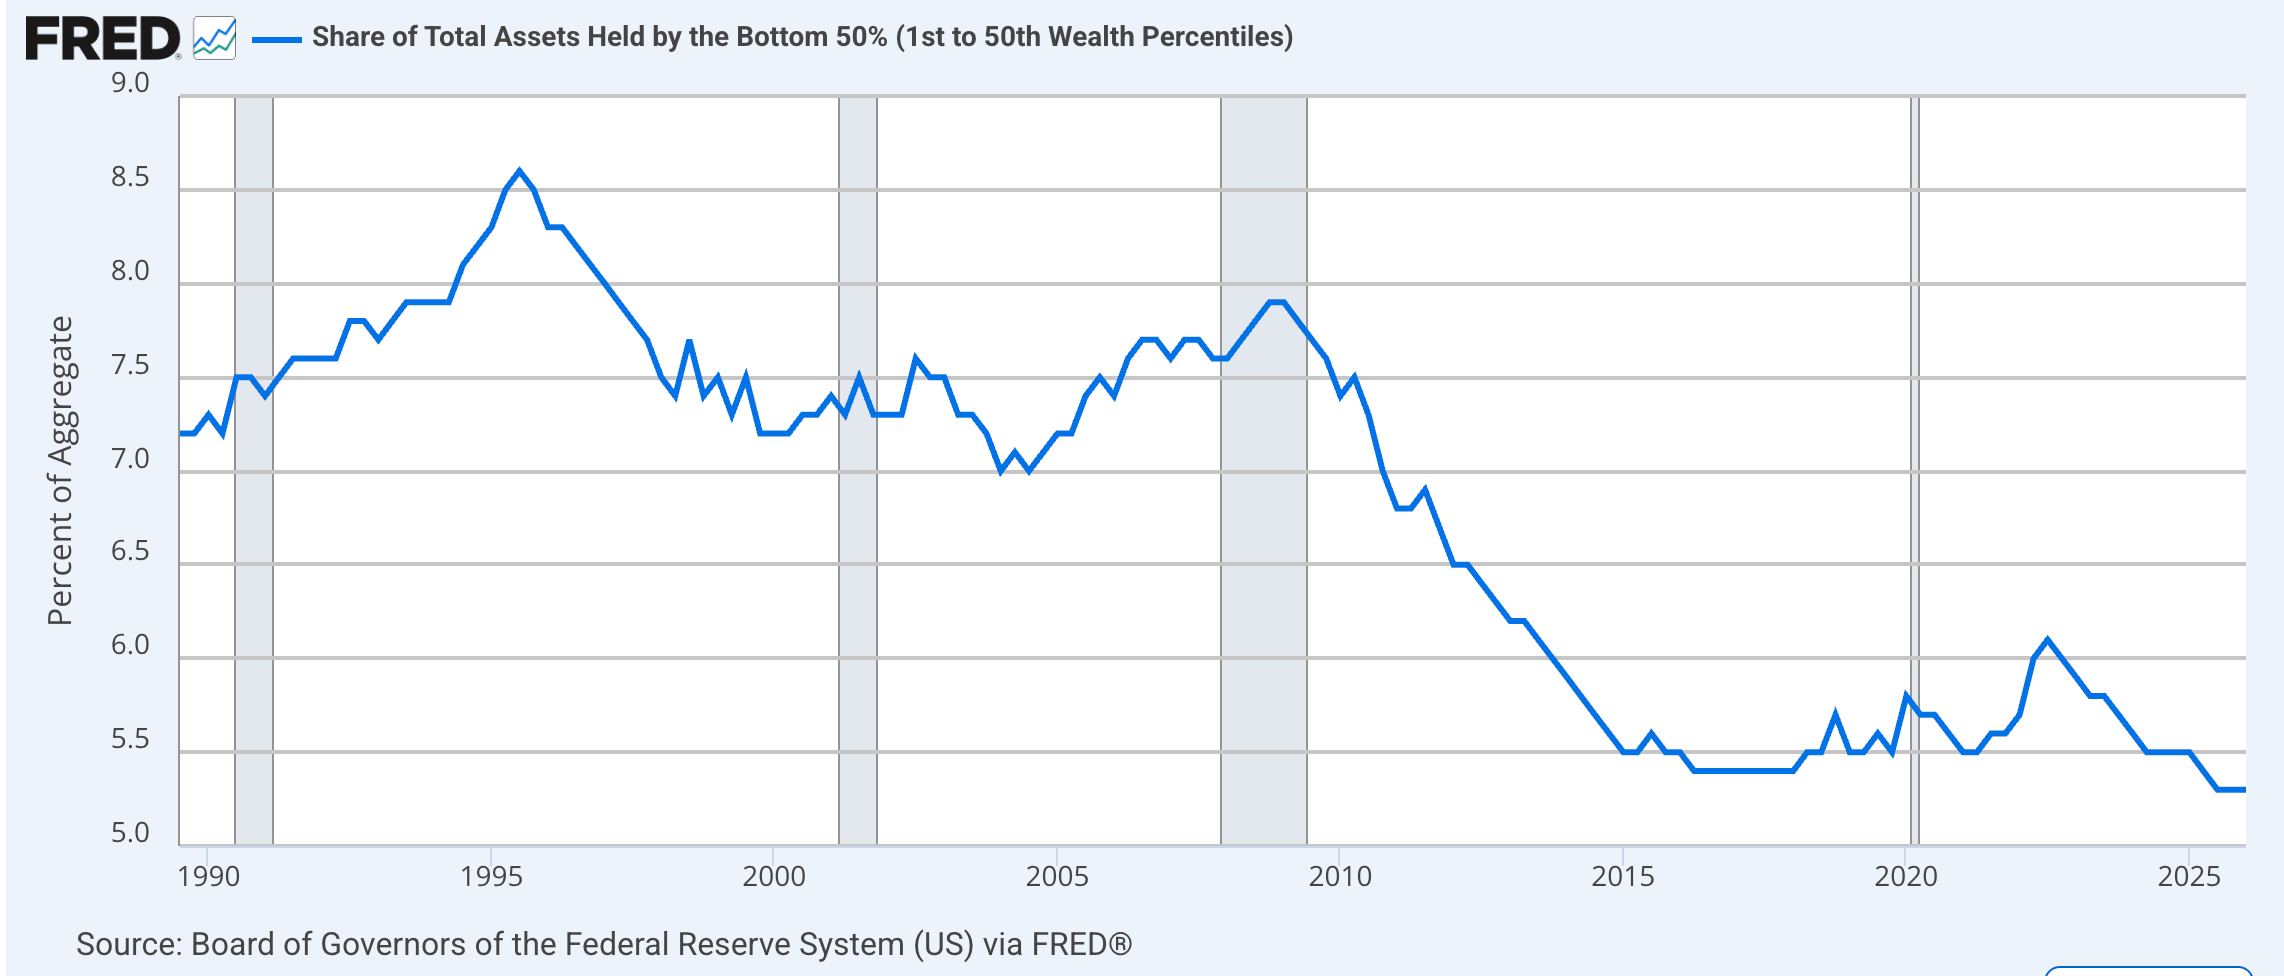
Federal Reserve distributional data reveal that wealth is increasingly concentrated. As of the fourth quarter of 2025, the richest 1% of Americans held 29.2% of the nation’s aggregate wealth (up from around 20% in the early 1990s), compared with just 5.3% for the bottom half.
Meanwhile, lower- and middle-income households are struggling. “Wage gains for most have been moderating, while essential costs for rent, groceries and gasoline remain elevated,” notes Schoeppner. “At the same time, savings buffers have continued to narrow while reliance on credit — particularly credit cards — has increased.”
Scott, what more evidence do you need? If this isn’t a K-shaped economy, what is it?
The labor market further reveals the K-shape. Hiring rates have fallen to 15-year lows of around 3.2% while layoff rates remain near historically low levels of 1.1%. In this “low-hire, low-fire” environment, workers who are already employed have some stability, but job seekers and those looking to advance are in trouble.
This is significant because mobility is the major way for workers to improve earnings, move into higher-productivity roles, and build financial buffers. “When hiring slows and job-switching premiums narrow,” says Beth Ann Bovino, U.S. Bank’s chief economist, “pathways to higher pay and better job matches become more limited.”
As a result, the labor market can appear stable at the aggregate level while becoming less dynamic beneath the surface — particularly for workers in lower-wage or more cyclical industries.
I’ve got to emphasize how badly the war in Iran is aggravating this K-shaped divide. U.S. Bank’s Schoeppner notes that “the resulting higher gasoline prices … may be more of an inconvenience for higher-income households, but for those with thinner buffers, they can quickly crowd out discretionary spending.” The San Francisco Fed has similarly noted that elevated gasoline and grocery costs are consuming a larger share of household budgets among the bottom 80%.
Credit conditions reveal the same widening divide. Bovino notes that lower-income households “tend to rely more heavily on higher-cost borrowing and devote a larger share of income to debt service, leaving them more sensitive to higher rates and reduced credit availability.” Recent Beige Book commentary also points to increased reliance on credit among lower-income households. The April 2026 Senior Loan Officer Opinion Survey shows tighter lending standards across key segments, suggesting that access to financing is becoming more constrained.
Scott, it’s important that you and your colleagues at the treasury and elsewhere in the Trump administration know what’s going on. The K-shaped economy can make the macro environment appear more stable than it is actually experienced by average working Americans. The fact is, the overall health of the economy increasingly depends on a narrowing base of consumption coming from the wealthy — who are spending because their stock market assets have risen so high but will stop spending if and when the stock market comes back to earth.
Meanwhile, inflation and credit pressures continue to land especially hard on lower-income Americans. In that sense, the K-shaped economy is not just a feature of recent cycles. It’s become the defining characteristic of how today’s economy absorbs shocks and generates growth.
Go ahead, Scott — attack me with all the ad hominem arguments you want. But you need to know the reality I’m talking about. You’re the one with the power. I’m just a retired professor. Your failure to comprehend the struggles facing average working Americans makes me worry that you and your boss will continue to pursue policies that worsen them.
Best wishes, Scott.
"Trump's right. His economy is a win for Wall Street. Meanwhile, while the rich get richer, millions of Americans cannot afford the basic necessities of life."
President Donald Trump on Friday said that the US economy is "doing unbelievably from the standpoint of Wall Street," bragging about record equity prices as job and wage growth remain stagnant and millions of Americans struggle to afford groceries.
In remarks to reporters, Trump hailed what he described as "the best market in history" as the S&P 500 index notched its third consecutive week of gains and hovered near its all-time high. The president, a prolific trader who has personally profited from the stock market's performance, said surging equities are "good for 401(k)s"—retirement accounts that a growing share of Americans are tapping to cover emergency expenses amid a worsening cost-of-living crisis.
"Trump's right. His economy is a win for Wall Street," Sen. Bernie Sanders (I-Vt.) said in response to the president. "Meanwhile, while the rich get richer, millions of Americans cannot afford the basic necessities of life—food, housing, healthcare, and a decent retirement."
The Alliance for Retired Americans, an advocacy group with more than 4 million members across the US, expressed astonishment at Trump's rosy and narrow assessment of the economy, which the White House posted on its official YouTube page.
"Can't make it up," the group wrote on social media. "We don't live on Wall Street. How is the economy working for you?"
Trump's comments came the same day that new data showed US consumer sentiment has fallen in August after two consecutive months of improvement, with Americans' outlook on the nation's economic conditions worsening across the political spectrum.
Last week, the Labor Department published figures showing that the US economy shed 23,000 jobs in July, wage growth decelerated, and the unemployment rate fell slightly as more people left the workforce.
Despite Trump's promise to bring them down, prices remain elevated across the economy, driven in part by the president's illegal war against Iran. Research published last month by the Urban Institute found that American families are increasingly relying on savings and credit—including buy now, pay later programs—to meet their grocery needs.
Americans are also facing what The Century Foundation and Protect Borrowers describe as "a worsening utility debt crisis."
"Energy bills have increased three times faster than the rate of inflation while Trump has been president," the groups wrote in an analysis published last month. "The national average monthly utility bill reached $280 in early 2026, a 12% increase since the end of 2024, just before the second Trump administration took office."
Meanwhile, corporate profits are booming under Trump, with the pharmaceutical industry, Big Oil, and other sectors posting banner earnings.
"Second quarter earnings for S&P 500 companies are on pace to rise 50% year over year, the highest growth rate since the second quarter of 2021," Yahoo Finance reported.